By Wiyao Awesso, Realtor®, VA Loan Specialist & Loan Officer, U.S. Navy veteran | DRE# 02058584 | NMLS# 1939042 | Updated November 2026
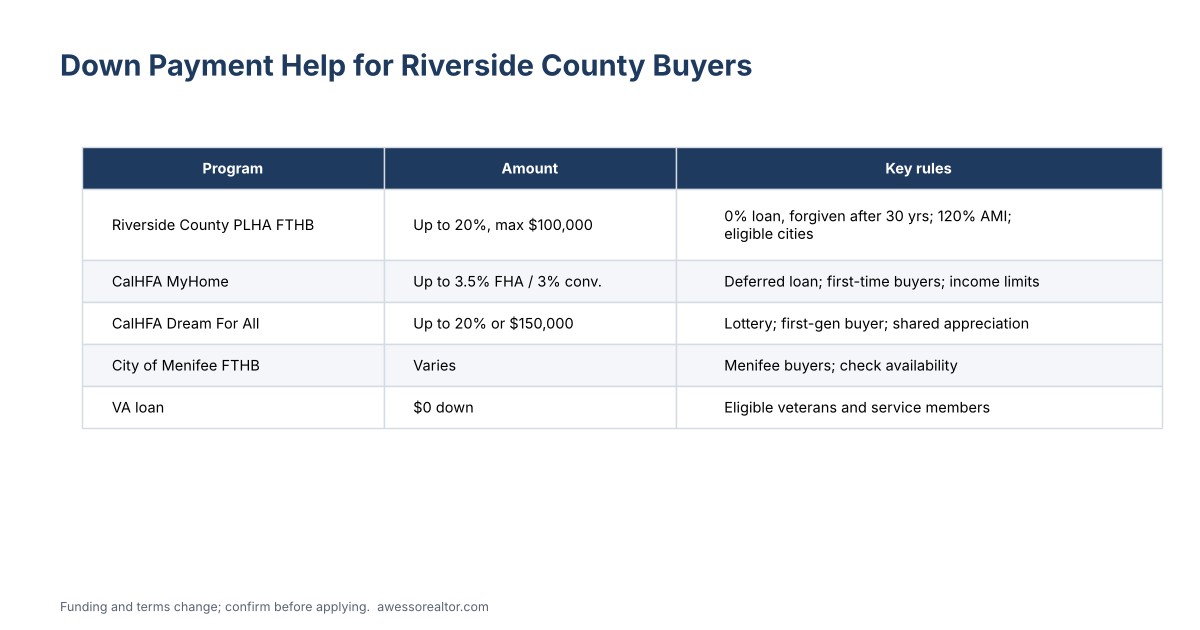
Quick answer: Riverside County buyers can combine several down payment assistance (DPA) programs. The biggest local option is Riverside County's PLHA First-Time Home Buyer program, which offers up to 20% of the price (capped at $100,000) as a no-payment, 0% loan forgiven after 30 years, for households at or below 120% of area median income in eligible cities like Murrieta, Temecula, Lake Elsinore and Hemet. Statewide, CalHFA's MyHome Assistance covers up to 3.5% on FHA loans or 3% on conventional loans, and the California Dream For All lottery can provide up to 20% or $150,000. VA buyers often need no down payment at all.
Riverside County PLHA First-Time Home Buyer Program
Riverside County Housing and Workforce Solutions runs this program with state Permanent Local Housing Allocation (PLHA) funds. Based on the county's 2025–2026 program flyer:
- Amount: up to 20% of the purchase price, capped at $100,000, for the down payment.
- Terms: a second loan with no monthly payments and no interest. The county holds a lien for 30 years, and the loan is forgiven at the end of that period if you meet the terms.
- Income: household income at or below 120% of area median income. For example, the limit is $124,680 for a family of four (effective July 1, 2025).
- First-time buyer: no homeownership in the past three years.
- Other: you must qualify for a first mortgage with an approved lender and be a U.S. citizen or qualified alien.
Eligible areas
The flyer lists Banning, Beaumont, Blythe, Canyon Lake, Cathedral City, Coachella, Desert Hot Springs, Eastvale, Hemet, Indio, Jurupa Valley, La Quinta, Lake Elsinore, Moreno Valley, Murrieta, Norco, Palm Springs, San Jacinto, Temecula, Wildomar and all unincorporated areas (such as French Valley and Winchester). Cities not on the list, like Menifee, Perris and Riverside, aren't shown as eligible, so check before you shop.
Funds are limited and can run out. Contact the county at fthb-programs@rivco.org or (951) 955-0784 for current availability.
| Household size |
Maximum income (120% AMI) |
| 1 |
$87,300 |
| 2 |
$99,720 |
| 3 |
$112,200 |
| 4 |
$124,680 |
| 5 |
$134,640 |
| 6 |
$144,600 |
CalHFA MyHome Assistance
CalHFA's MyHome Assistance is a deferred-payment junior loan for first-time buyers using a CalHFA first mortgage:
- Up to 3.5% of the price or appraised value with a CalHFA FHA loan.
- Up to 3% with a CalHFA Conventional loan.
- Can be used for down payment, closing costs or both.
- Requires homebuyer education and CalHFA income limits.
Learn more in my guide to CalHFA loans for first-time buyers.
California Dream For All
Dream For All is a shared-appreciation loan of up to 20% of the price or $150,000. It's awarded by lottery during short application windows. The 2026 round ran February 24 to March 16. At least one borrower must be a first-generation buyer, and all must be first-time buyers within CalHFA income limits. When you sell or refinance, you repay the original amount plus a share of the home's appreciation. Watch CalHFA's website for the next round.
City and Nonprofit Programs
- City of Menifee First-Time Homebuyer Assistance: Menifee runs its own program, administered with a local nonprofit partner.
- Neighborhood Partnership Housing Services (NPHS): an Inland Empire nonprofit that offers homebuyer education and deferred DPA loans for eligible buyers.
- Golden State Finance Authority (GSFA): statewide programs that pair a first mortgage with assistance.
- Employer and credit union programs: some employers and local credit unions offer closing cost help.
Program terms change often. Confirm the details before you apply.
VA Buyers: You May Not Need DPA
Eligible veterans and service members can buy with no down payment and no monthly mortgage insurance using a VA loan. You still need cash for closing costs, though sellers can pay some of them. See buying near March ARB with a VA loan.
Can You Stack Programs?
Sometimes. A buyer might use a CalHFA first mortgage with MyHome Assistance plus a county or city loan, if each program allows it. Each program sets rules for combined loan amounts, income limits and which first mortgages it works with. Your lender has to confirm the combination.
Pros and Cons of Down Payment Assistance
| Pros |
Cons |
| Buy sooner with less cash |
Income and price limits |
| Deferred or forgivable loans |
Some must be repaid when you sell or refinance |
| Can lower your monthly payment |
Some programs share appreciation |
| Free homebuyer education |
Funds can run out; closings may take longer |
How to Apply
- Check your household income against each program's limits.
- Take a homebuyer education course (many programs require it).
- Get pre-approved with a lender approved for the program. Apply here.
- Shop for homes in eligible cities and under any price limits.
- Your lender reserves the DPA funds once you're in contract.
Mistakes to Avoid
- Falling in love with a home in a city the program doesn't cover.
- Assuming every DPA is a grant. Most are loans.
- Waiting until you're in escrow to check funding availability.
- Not reading the repayment terms if you sell or refinance early.
Example: How DPA Changes Your Cash to Close
Here's a simple example on a $500,000 home with an FHA loan:
| Item |
Without DPA |
With 3.5% CalHFA MyHome |
| Down payment (3.5%) |
$17,500 |
Covered by MyHome |
| Closing costs (example) |
$12,000 |
$12,000 (seller credits may help) |
| Cash needed (before reserves) |
About $29,500 |
About $12,000 |
This is an illustration only. Your lender will confirm actual costs and program limits.
Homebuyer Education
Most assistance programs require a homebuyer education course. CalHFA accepts the eHome online course or live counseling through a HUD-approved agency. Local nonprofits such as Neighborhood Partnership Housing Services also offer classes. Take it early, because certificates are usually valid for a year and some programs won't reserve funds without one.
Questions to Ask Before You Choose a Program
- Is it a grant, a forgivable loan or a deferred loan?
- What happens if I sell or refinance in the first five years?
- Does it share in my home's appreciation?
- Does it raise my interest rate or fees?
- How long does approval take, and are funds available now?
Related Guides
Frequently Asked Questions
How much do I need to save to buy in Riverside County?
With DPA or a VA loan, some buyers need only closing costs and reserves. Without help, FHA needs 3.5% down and some conventional loans allow 3%, plus closing costs of about 2% to 5%.
Does Riverside County have a first-time homebuyer program?
Yes. The county's PLHA First-Time Home Buyer program offers up to 20% of the price, capped at $100,000, for eligible buyers in participating cities.
Is down payment assistance free money?
Usually not. Most programs are deferred or forgivable loans. Some are repaid when you sell or refinance, and some share appreciation.
How long does it take?
Expect a little more time to close than a standard loan, often 30 to 60 days, because the program must review and fund the assistance.
Find Out What You Qualify For
I'm a Realtor® and U.S. Navy veteran who helps first-time buyers find homes that fit assistance program rules. Call or text 951-282-7007 or apply for a home loan.
#DownPaymentAssistance #FirstTimeHomeBuyer #RiversideCounty #CalHFA #DreamForAll #Murrieta #Temecula #LakeElsinore #Hemet #InlandEmpire #HomeBuying
Sources: Riverside County Housing and Workforce Solutions (PLHA FTHB 2025–2026 flyer); CalHFA MyHome Assistance; CalHFA Dream For All 2026 announcement; Neighborhood Partnership Housing Services. Program funding, income limits and terms change. This article is general information, not legal, tax or financial advice.
About the Author
Wiyao Awesso
Realtor® | VA Loan Specialist & Loan Officer | U.S. Navy Veteran
Wiyao is a Murrieta-based Realtor® and licensed loan officer who specializes in VA loans and military relocation. After about 20 years in the U.S. Navy, he helps service members, veterans and first-time buyers buy, sell and finance homes across Riverside and San Diego counties, from the first showing to the closing table.
DRE# 02058584 | NMLS# 1939042 | 951-282-7007 | More about Wiyao
Get a VA Loan QuoteApply Now