By Wiyao Awesso, Realtor®, VA Loan Specialist & Loan Officer, U.S. Navy veteran | DRE# 02058584 | NMLS# 1939042 | Updated November 2026
Quick answer: A bank-owned (REO) home is a property the lender took back after it didn't sell at a foreclosure auction. You buy it much like a regular home: get pre-approved, tour it, make an offer through your agent, and inspect it. The differences are that the bank sells it as-is, uses its own addendum that overrides parts of the standard California contract, often takes longer to respond, and may charge a daily penalty if you close late.
What "REO" Means
REO stands for "real estate owned." When a homeowner can't pay and the home goes to a trustee sale, investors can bid on it. If nobody bids enough to cover what the lender is owed, the property goes back to the lender. The lender then cleans it out, changes the locks, orders a broker price opinion, and lists it on the MLS with a local listing agent. That's the point where everyday buyers, not just cash investors, can buy it.
Because the lender never lived in the home, it usually knows very little about its condition. That's why REO sales come with limited disclosures and an as-is clause.
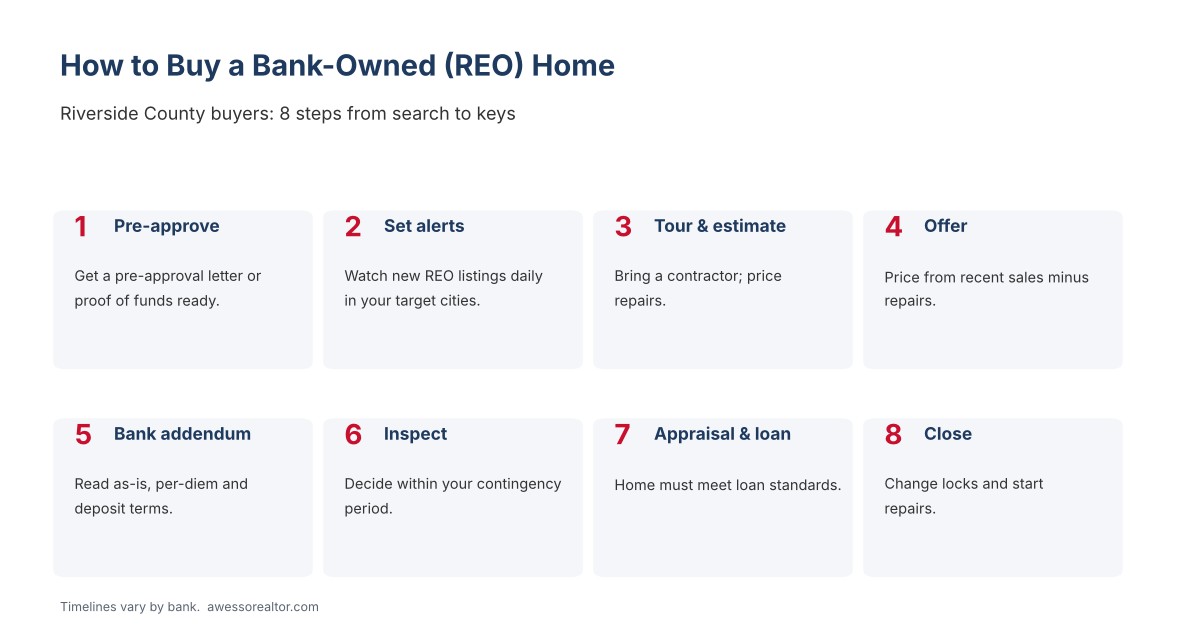
The REO Buying Process, Step by Step
- Get pre-approved or gather proof of funds. Banks often want to see a pre-approval letter or a bank statement with the offer. Start a pre-approval.
- Set up alerts for new REO listings. Good bank-owned homes in Murrieta, Temecula and Menifee can get multiple offers in the first week. I set up alerts so you see them the day they hit the market.
- Tour the home and check the utilities. Many REOs are winterized with the water off. Ask whether utilities can be turned on for the inspection.
- Estimate repairs. Bring a contractor if you can, and price out the roof, HVAC, plumbing, flooring and paint.
- Write the offer. Your agent writes it on the standard California purchase agreement with your price, financing and contingencies.
- Review the bank's addendum. If the bank accepts or counters, it sends its own addendum. Read it carefully before you sign (more on that below).
- Inspect during your contingency period. Decide whether to move forward, ask for a credit, or cancel.
- Appraisal and loan approval. The home must meet your loan's property standards.
- Close escrow. Change the locks, set up utilities and start repairs.
The Bank's Addendum: What to Watch For
REO sellers almost always add their own addendum to the contract. It takes priority over the standard form where they conflict. Common terms include:
- As-is sale: the bank won't make repairs, though it may allow you to cancel during your inspection period.
- Limited disclosures: as a lender that never lived there, the bank is usually exempt from some seller disclosure forms.
- Per-diem penalty: a daily fee if you close after the agreed date, even if the delay isn't your fault.
- Seller's choice of escrow and title in some cases.
- Shorter or fixed deadlines for inspections and loan approval.
- Earnest money terms that may make your deposit harder to get back after contingencies are removed.
Have your agent walk you through every paragraph. If anything is unclear, a real estate attorney can review it.
Can You Use a Loan on an REO?
Yes, as long as the home meets the loan's condition standards. Here's how the main loan types handle bank-owned homes:
| Loan type |
Works on REOs? |
Watch for |
| Conventional |
Yes |
Home must be livable; major damage can stop the loan |
| FHA |
Yes, if it meets FHA standards |
Peeling paint, missing appliances, roof or safety issues |
| VA |
Yes, if it meets VA minimum property requirements |
Same as FHA; repairs may be required before closing |
| FHA 203(k) / renovation |
Yes |
Rolls repair costs into the loan; takes longer |
| Cash |
Yes |
Strongest offer; still inspect |
Are REO Homes Really Cheaper?
Sometimes. Banks price REOs using market data, so the list price is often close to what similar homes in fair condition sell for. The real discount comes from condition: a home that needs paint, flooring and landscaping may sell for less than a move-in-ready home down the street. Compare the price plus your repair budget with recent sales of updated homes nearby. If the math doesn't leave you with equity or a fair deal, pass.
How to Make a Strong Offer on a Bank-Owned Home
- Offer with a clean structure: clear financing, realistic deadlines, and proof of funds.
- Price with data: recent comparable sales minus your repair estimate.
- Respond fast: banks often send counteroffers with short deadlines.
- Be ready to sign the addendum quickly once you understand it.
- Don't over-ask for repairs: the bank usually won't do them, so negotiate on price instead.
Common REO Problems Found at Inspection
- Water leaks and mold, especially if the home sat vacant
- Missing appliances, fixtures or copper pipes
- Roof wear and pool equipment that hasn't run in months
- Termite damage (ask for a wood-destroying pest report)
- Unpermitted additions or garage conversions
REO vs. Short Sale vs. Auction
| |
REO (bank-owned) |
Short sale |
Trustee sale auction |
| Who sells |
The lender |
The homeowner, with lender approval |
The trustee |
| Inspection |
Yes |
Yes |
Usually no interior access |
| Financing |
Yes |
Yes |
Usually cash only |
| Timeline |
About 30–45 days after acceptance |
Often months for lender approval |
Same day; possession can take longer |
| Risk level |
Moderate |
Moderate (deal can fall through) |
High |
For a full overview of every type, read how to buy a foreclosure in Riverside County.
HUD Homes and Fannie Mae HomePath
Some REOs are owned by government agencies. HUD sells homes from foreclosed FHA loans through HUDHomestore.gov, and Fannie Mae sells its foreclosures through HomePath. These often give owner-occupants a priority period before investors can bid. Offers go through a registered agent, and bidding rules differ from regular REOs.
Where to Find Bank-Owned Homes in Southwest Riverside County
REOs show up on the MLS across Murrieta, Temecula, Menifee, Perris, Hemet and Lake Elsinore. See current foreclosures and bank-owned homes.
REO Timeline: What to Expect
| Stage |
Typical time |
| Offer to bank response |
A few days to two weeks |
| Counteroffer and addendum signing |
1–3 days |
| Inspection contingency |
Often 7–17 days, per the contract |
| Appraisal and loan approval |
2–4 weeks |
| Close of escrow |
About 30–45 days after acceptance |
Build in a cushion for your move-out date or lease, because bank approvals and signatures can add days.
Budgeting for a Bank-Owned Home
Beyond the price and normal closing costs, plan for:
- Inspections: general, roof, sewer line camera, pool and termite.
- Utility turn-on: some banks require the buyer to arrange it for inspections.
- Re-keying and cleaning: change every lock on day one.
- Immediate repairs: items your lender or insurer may require before or right after closing.
- Holding costs: mortgage, taxes, insurance and utilities while you fix the home.
Owner-Occupant vs. Investor
Owner-occupants can use low-down-payment loans and may get priority on HUD and HomePath homes during first-look periods. Investors usually compete with cash and faster closings. If you plan to live in the home, say so in your offer, and be honest on every loan and program application.
Mistakes First-Time REO Buyers Make
- Skipping the inspection because the home is "as-is." As-is doesn't mean uninspected.
- Signing the bank addendum without reading the per-diem and deposit terms.
- Using all their cash on the down payment with nothing left for repairs.
- Assuming an FHA or VA loan will work on a home with major damage.
Related Guides
Frequently Asked Questions
Can I get a loan to buy a bank-owned home?
Yes. Conventional, FHA and VA loans can work if the home meets the loan's condition standards. Homes with major damage may need cash or a renovation loan.
Do banks negotiate on REO prices?
Often, especially if a home has been on the market for a while or has repair issues. Banks usually counter rather than accept a low offer outright.
Will the bank make repairs?
Usually not. REOs are sold as-is, so negotiate on price and budget for repairs yourself.
How long does it take to buy an REO?
Expect a few days to a couple of weeks for the bank to respond, then about 30 to 45 days to close with financing.
Want Help Buying a Bank-Owned Home?
I'm a Realtor® and U.S. Navy veteran who helps buyers read bank addenda, estimate repairs and write offers that get accepted. Call or text 951-282-7007 or see current bank-owned homes.
#REO #BankOwnedHomes #Foreclosures #RiversideCounty #MurrietaRealEstate #TemeculaRealEstate #Menifee #InlandEmpire #FixerUpper #HomeBuying #RealEstateInvesting
Sources: U.S. Department of Housing and Urban Development (HUDHomestore); Fannie Mae HomePath; California Department of Real Estate. Bank addenda vary by seller. This article is general information, not legal, tax or financial advice. Have a real estate attorney review contract terms if you have questions.
About the Author
Wiyao Awesso
Realtor® | VA Loan Specialist & Loan Officer | U.S. Navy Veteran
Wiyao is a Murrieta-based Realtor® and licensed loan officer who specializes in VA loans and military relocation. After about 20 years in the U.S. Navy, he helps service members, veterans and first-time buyers buy, sell and finance homes across Riverside and San Diego counties, from the first showing to the closing table.
DRE# 02058584 | NMLS# 1939042 | 951-282-7007 | More about Wiyao
Get a VA Loan QuoteApply Now