By Wiyao Awesso, Realtor®, VA Loan Specialist & Loan Officer, U.S. Navy veteran | DRE# 02058584 | NMLS# 1939042 | Updated November 2026
Quick answer: To find Murrieta foreclosures, set up MLS alerts for bank-owned (REO) and short sale listings, watch HUD and Fannie Mae HomePath sites, and track trustee sale notices if you're a cash investor. Most buyers do best with bank-owned homes listed by an agent, because you can inspect and use a loan. Get pre-approved, budget for repairs, and make sure the home fits your loan's property standards before you write an offer.
Are There Foreclosures in Murrieta Right Now?
Yes, though not many compared with the 2008 era. ATTOM reports that foreclosure activity rose in 2026 compared with 2025, but filings are still low by historical standards and most Murrieta homeowners have equity. That means distressed listings appear regularly but sell fast when priced well. Speed and preparation matter. See current Murrieta foreclosures and bank-owned homes.
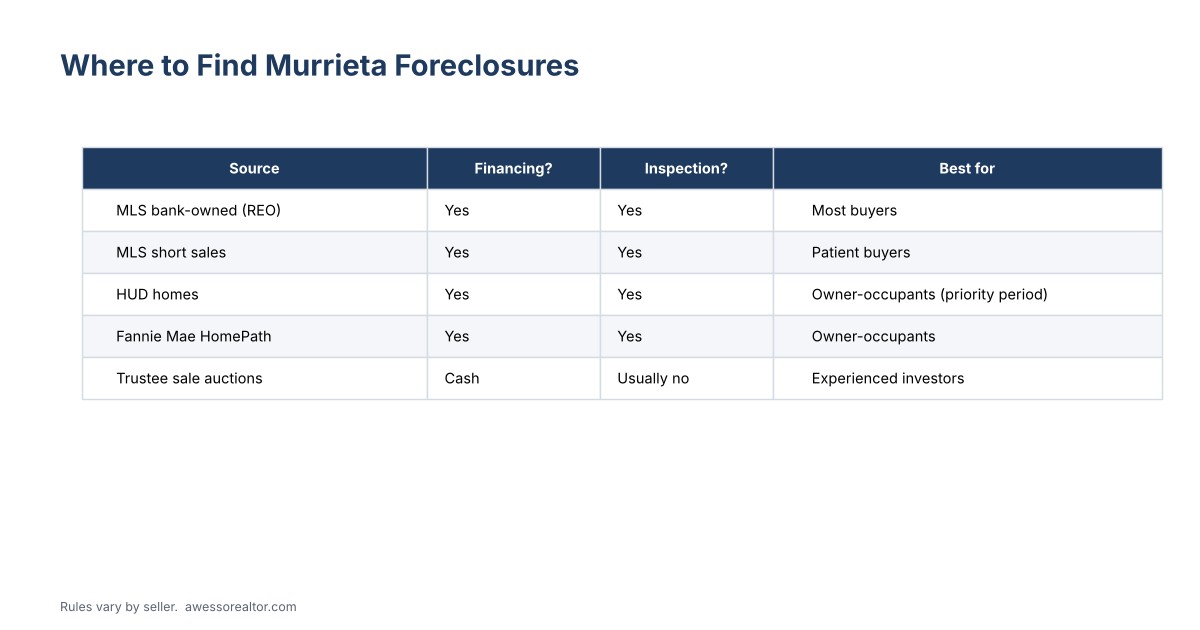
Where to Find Murrieta Foreclosures
1. The MLS (bank-owned and short sales)
Almost every bank-owned home is listed on the MLS by a local listing agent. Short sales are listed there too. I set up instant alerts filtered for REO and short sale listings in Murrieta, French Valley, Wildomar and nearby cities.
2. HUD homes
Foreclosed FHA homes are sold on HUDHomestore.gov, often with an owner-occupant priority period.
3. Fannie Mae HomePath and Freddie Mac HomeSteps
These agencies sell their own foreclosures, sometimes with first-look periods for owner-occupants.
4. Trustee sale auctions
Notices of Trustee Sale are recorded with the Riverside County Recorder and published. Auctions usually require cash and give you no interior access, so they're best for experienced investors.
5. Pre-foreclosures
Homes with a recorded Notice of Default may be listed for sale by owners trying to avoid foreclosure. Approach these owners respectfully, and be aware of California's rules protecting homeowners in foreclosure.
Murrieta Neighborhoods Where Distressed Homes Appear
Foreclosures can show up anywhere, from older homes near Historic Downtown to newer tracts on the east side and larger lots in Los Alamos Hills. Newer neighborhoods with higher Mello-Roos and HOA dues can see more owners stretched by rising costs. Learn the areas in my guide to the best neighborhoods in Murrieta.
How to Buy a Murrieta Foreclosure
- Get pre-approved or gather proof of funds. Apply here.
- Set up REO and short sale alerts for Murrieta and nearby areas.
- Tour fast and bring a contractor if you can.
- Price your offer using recent Murrieta sales minus repair costs.
- Review the bank's addendum carefully. See how the REO buying process works.
- Inspect and decide within your contingency period.
- Close escrow, change the locks and start repairs.
Can You Use a Loan on a Murrieta Foreclosure?
Yes, if the home meets the loan's standards. FHA and VA loans need homes that are safe and livable, without peeling paint, missing appliances or roof problems. Homes with bigger issues may need cash, a conventional loan, or a renovation loan like an FHA 203(k).
Is a Murrieta Foreclosure Really Cheaper?
Often a little, but not always. Banks price using recent sales, and competition from investors can push prices up. The best deals usually come from homes that need cosmetic work like paint, flooring and landscaping that scare off other buyers. Compare:
| Item |
Example |
| Recent sale of an updated home nearby |
$700,000 |
| Foreclosure list price |
$630,000 |
| Estimated repairs |
$40,000 |
| Total cost |
$670,000 |
| Potential equity |
About $30,000, before holding costs |
These numbers are an illustration, not a market report.
Risks to Plan For
- Hidden water damage, mold or plumbing issues from vacancy
- Back HOA dues or liens (check the title report)
- Unpermitted additions or garage conversions
- Pools and septic systems that haven't been maintained
- Bank delays and per-diem penalties for late closing
Tips From a Local Agent
- Check Mello-Roos and HOA dues. They don't go away because the home was foreclosed.
- Ask for utilities to be turned on for the inspection.
- Get a sewer line camera inspection on older homes.
- Have a backup plan if the bank counters above your budget.
Behind on Your Own Mortgage?
If you're a Murrieta homeowner who's struggling, you have options before foreclosure, including selling while you still have equity. Read can't afford your mortgage? Your options in California.
Foreclosure Terms You'll See on Listings
| Term |
What it means |
| REO / bank-owned |
The lender owns the home and sells it through an agent |
| Short sale |
The owner sells for less than owed, with lender approval |
| Notice of Default (NOD) |
The first recorded notice that a homeowner is behind |
| Notice of Trustee Sale (NOTS) |
Sets the auction date, at least 20 days out |
| As-is |
The seller won't make repairs |
| HUD home |
A foreclosed FHA home sold by HUD |
Short Sales in Murrieta
Short sales are often in better condition than bank-owned homes because the owners still live there. The catch is time: the lender must approve the price, which can take weeks or months, and the deal can fall apart. If you're flexible on timing, a short sale can be a good way to buy a well-kept home below typical prices.
Investing in Murrieta Foreclosures
Investors look at Murrieta for rentals and fix-and-flips because of steady demand from families and military households. Run the numbers carefully: purchase price, repairs, holding costs, selling costs or expected rent, Mello-Roos, HOA rules on rentals, and insurance. A home that works as a rental near I-215 might not work as a flip, and vice versa.
Related Guides
Frequently Asked Questions
How do I find foreclosures in Murrieta?
Set up MLS alerts for bank-owned and short sale listings, check HUDHomestore and HomePath, and watch recorded trustee sale notices if you're a cash investor.
Can I get a loan for a Murrieta foreclosure?
Yes, for most bank-owned homes and short sales that meet the loan's condition standards. Auctions usually require cash.
Are foreclosures cheaper in Murrieta?
Sometimes. Compare the price plus repairs with recent sales of updated homes nearby before you decide.
What are the risks?
Hidden repairs, as-is condition, liens or back dues, and bank delays. A thorough inspection and title review reduce the risk.
Get Murrieta Foreclosure Alerts
I'm a Realtor® and U.S. Navy veteran who lives and works in the Murrieta area. I'll set up alerts for new bank-owned and short sale listings and help you write offers that work. Call or text 951-282-7007 or see current listings.
#MurrietaForeclosures #Murrieta #BankOwnedHomes #REO #ShortSale #Foreclosures #MurrietaRealEstate #RiversideCounty #FixerUpper #RealEstateInvesting #HomeBuying
Sources: ATTOM 2026 mid-year foreclosure report; U.S. Department of Housing and Urban Development; Fannie Mae HomePath; Riverside County Assessor-County Clerk-Recorder; California Civil Code §§ 2924–2924m and 1695 (home equity sales contracts). This article is general information, not legal, tax or financial advice. Consult a real estate attorney before bidding at a trustee sale.
About the Author
Wiyao Awesso
Realtor® | VA Loan Specialist & Loan Officer | U.S. Navy Veteran
Wiyao is a Murrieta-based Realtor® and licensed loan officer who specializes in VA loans and military relocation. After about 20 years in the U.S. Navy, he helps service members, veterans and first-time buyers buy, sell and finance homes across Riverside and San Diego counties, from the first showing to the closing table.
DRE# 02058584 | NMLS# 1939042 | 951-282-7007 | More about Wiyao
Get a VA Loan QuoteApply Now