By Wiyao Awesso, Realtor®, VA Loan Specialist & Loan Officer, U.S. Navy veteran | DRE# 02058584 | NMLS# 1939042 | Updated November 2026
Quick answer: Forbearance pauses or lowers your mortgage payments for a set time, but the skipped amount still has to be dealt with later. A repayment plan adds part of your past-due balance to your regular payment over several months until you're caught up. A loan modification permanently changes your loan terms, such as the rate, term or balance, to make the payment more affordable. Forbearance fits short-term hardships, repayment plans fit people who are back on their feet, and modifications fit long-term income changes.
The Three Options at a Glance
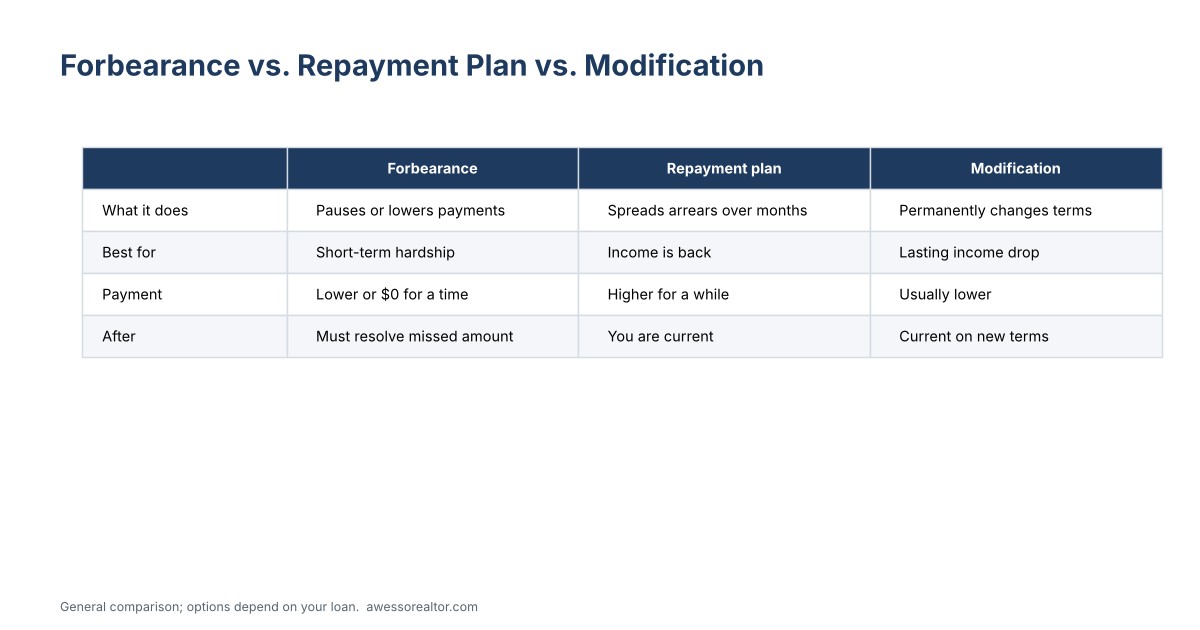
| |
Forbearance |
Repayment plan |
Loan modification |
| What it does |
Pauses or reduces payments temporarily |
Spreads past-due amount over a few months |
Permanently changes loan terms |
| Best for |
Short-term hardship |
Income is back; you can pay extra |
Lasting drop in income |
| Monthly payment |
Lower or zero during forbearance |
Higher for a while |
Usually lower going forward |
| Length |
Often a few months, sometimes extended |
Often 3–12 months |
Rest of the loan |
| Paperwork |
Light |
Light to moderate |
Full financial review, often a trial period |
| What happens after |
Must resolve the missed amount |
You're current |
You're current under new terms |
Forbearance
Forbearance is an agreement to pause or reduce your payments for a set period, such as three to six months. Interest typically keeps accruing. It's designed for temporary hardships like a job loss with a new job coming, a medical event, or a natural disaster.
What happens when forbearance ends
This is the part many people misunderstand. Forbearance doesn't forgive the missed payments. At the end, the servicer reviews you for a way to handle them, which may include:
- Paying the full amount at once (reinstatement), if you can
- A repayment plan
- A payment deferral, which moves missed payments to the end of the loan
- A partial claim for FHA and VA loans
- A loan modification
Ask exactly what your exit options will be before you agree to forbearance.
Repayment Plan
A repayment plan lets you catch up by paying your normal payment plus a portion of the past-due amount each month. For example, if you're $6,000 behind, a six-month plan would add about $1,000 a month to your payment.
- Pros: quick to set up, no change to your loan terms, you're current at the end.
- Cons: the higher payment can be hard to keep up. If you miss a plan payment, the plan may be cancelled.
Only agree to a plan you can realistically afford every month.
Loan Modification
A modification permanently changes your loan to make the payment affordable. Depending on the program, it can:
- Add the past-due amount to the loan balance
- Extend the term, for example to 40 years
- Lower the interest rate
- Defer part of the principal as a non-interest-bearing balance due at payoff
Modifications usually require a complete application with income documents, a hardship letter and bank statements, followed by a trial period of about three monthly payments. If you make all trial payments on time, the modification becomes permanent.
Options by Loan Type
| Loan |
Common options |
| Conventional (Fannie Mae / Freddie Mac) |
Forbearance, repayment plan, payment deferral, Flex Modification |
| FHA |
Forbearance, repayment plan, partial claim, FHA modification options |
| VA |
Repayment plan, forbearance, modification (up to 40 years), VA Partial Claim Program launched in 2026 |
| USDA |
Forbearance, repayment plan, modification, mortgage recovery advance |
| Portfolio / private loans |
Varies by lender |
Program details change, so ask your servicer what's available for your specific loan.
How Each Option Can Affect Your Credit
- Forbearance: servicers report it in different ways. Ask how yours will be reported, and check your credit reports.
- Repayment plan: the earlier missed payments may already show as late; on-time plan payments help you recover.
- Modification: may be noted on your report, but it's generally far less damaging than foreclosure.
How to Choose
- Is the hardship temporary? If yes, forbearance or a repayment plan may be enough.
- Can you afford your normal payment again? If yes, plus a little extra, a repayment plan works.
- Has your income dropped for the long term? A modification is likely the better fit.
- Is the home simply unaffordable? Selling while you have equity, or a short sale, may be the smarter path.
When Selling Is Better Than Any Plan
If none of these options leaves you with a payment you can sustain, selling may protect your credit and equity better than stretching for a plan that fails. Find out what your home is worth and read how to sell your house in Murrieta.
Payment Deferral and Partial Claims
Two other options often come up when forbearance ends:
- Payment deferral: available on many Fannie Mae and Freddie Mac loans. Missed payments become a non-interest balance due when you sell, refinance or pay off the loan. Your monthly payment stays the same.
- Partial claim: for FHA loans, and VA loans under the 2026 VA Partial Claim Program. The missed amount is moved into a separate, interest-free junior lien repaid when you sell, refinance or pay off the loan.
Example: Same Hardship, Three Outcomes
Say you missed four payments of $3,000 ($12,000 total):
| Option |
What happens |
| Repayment plan (12 months) |
Pay $3,000 + $1,000 = $4,000 a month for a year |
| Payment deferral / partial claim |
$12,000 moved to the end or a separate lien; payment stays $3,000 |
| Loan modification |
$12,000 added to the balance; term or rate changed so payment may drop |
These are illustrations only. Your servicer determines eligibility and terms.
Questions to Ask Before You Agree
- What will my payment be, and for how long?
- What happens if I miss a payment under this plan?
- How will this be reported to the credit bureaus?
- Are late fees waived?
- Can I get the terms in writing before I accept?
Related Guides
Frequently Asked Questions
Is forbearance the same as forgiveness?
No. Forbearance pauses or lowers payments temporarily. The missed amount must still be repaid or resolved through another option.
Which is better, a repayment plan or a modification?
A repayment plan is better if your income is back and you can afford a higher payment for a few months. A modification is better if your income has dropped for good.
How long does a loan modification take?
Often a few months: the application review, then a trial period of about three payments before it becomes permanent.
Can I get a modification on a VA loan?
Yes. VA servicers can offer modifications, including terms up to 40 years, and VA launched a partial claim program in 2026.
Talk Through Your Options
Call or text me at 951-282-7007 for a confidential conversation about your home's value and whether keeping or selling makes more sense.
#MortgageForbearance #LoanModification #RepaymentPlan #ForeclosurePrevention #MortgageHelp #VALoan #FHA #California #RiversideCounty #Murrieta #Homeowners
Sources: Consumer Financial Protection Bureau; Fannie Mae and Freddie Mac servicing guides; U.S. Department of Housing and Urban Development; NAR on the VA Partial Claim Program. Programs change and depend on your loan. This article is general information, not legal, tax or financial advice.
About the Author
Wiyao Awesso
Realtor® | VA Loan Specialist & Loan Officer | U.S. Navy Veteran
Wiyao is a Murrieta-based Realtor® and licensed loan officer who specializes in VA loans and military relocation. After about 20 years in the U.S. Navy, he helps service members, veterans and first-time buyers buy, sell and finance homes across Riverside and San Diego counties, from the first showing to the closing table.
DRE# 02058584 | NMLS# 1939042 | 951-282-7007 | More about Wiyao
Get a VA Loan QuoteApply Now